How to use Credit Wisely

Debt-to-income or debt-burden ratio
Your debt-to-income ratio usually gives a clear picture of your financial well-being. To calculate it, add up your fixed monthly debt payments, such as car loan or mortgage payments (you do not have to include expenses like utilities or groceries). Then divide the total by your monthly take-home pay.
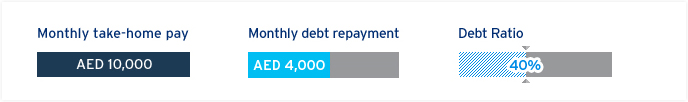
Your ratio gives lenders a good indication of how much additional credit you will be able to handle. The Central Bank of the U.A.E has limited the debt-to-income ratio for unsecured consumer loans to 50%.
Creditors look at several key indicators when you apply for credit. You have considerable control over these factors based on how you manage your credit, so it's important to always keep them in mind.
The 3 Cs of good credit
Client History
How responsible you are about paying bills on time.
Capacity
Your ability to pay back a loan based on your income and financial position.
Collateral
Security for the lender in case you don't pay back the loan. A house, for example, would be used to collateralize a mortgage.
Positively changing your "3 Cs" will help improve your credit standing. The first two Cs are extremely important in developing your credit rating.
Maintaining Good Credit
Once you have credit, you begin to build a credit history. Lenders use your credit history to gauge your ability to repay. So, a good or bad credit history can make a big difference in getting the loan, credit card or mortgage you need.
To maintain a good credit history, try practicing the following guidelines:
- Pay at least the minimum payment due-on time, every month.
- Don't overextend yourself. The fewer accounts you have open-whether they are loans or credit cards-the better.
- Don't spend income now that you hope to make later.
- Avoid transferring balances unless you're definitely getting a better interest rate.
- Notify creditors when you move so that bills arrive on time and your payments are never late. Even if you don't get your bill, you still owe the payment. If your due date is coming up and you haven't received a statement, visit the Online Banking website or call the Customer Service number located on your credit card or previous statement. Customer Service can tell you minimum payment due and where to send the check.